Square froze a verified small business account and provided no clear explanation
A digital marketing firm submitted all required legal and financial documents to Square, yet the platform suspended the account and denied the appeal without citing a specific reason.
By Alexei Malhotra ·
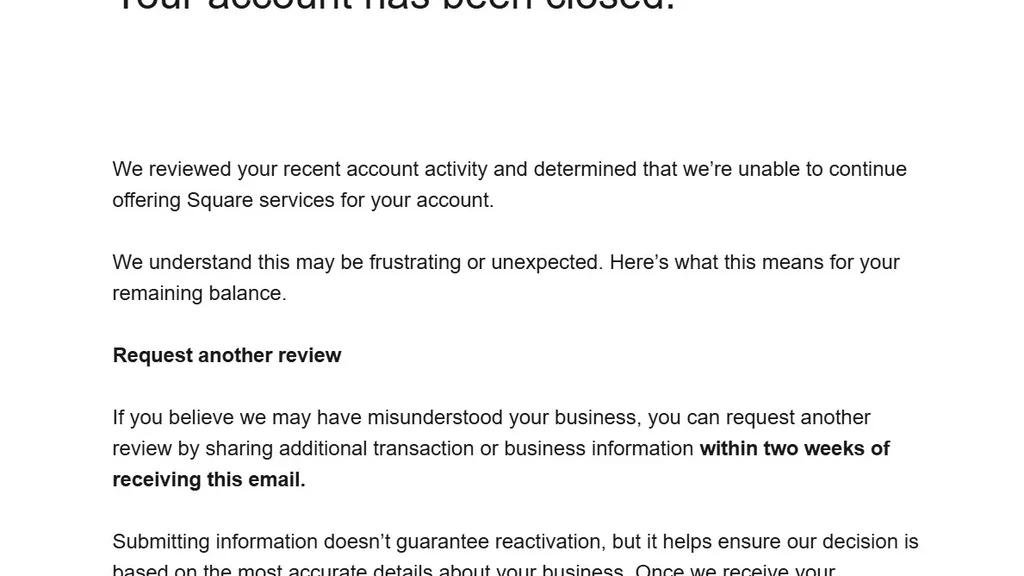
A small marketing and search engine optimization firm followed every step of the verification process for its payment processing account. The business provided government issued identification, a valid Employer Identification Number from the Internal Revenue Service, and formal LLC formation documents. It linked a confirmed business bank account using third party software and held a signed contract with a client for the full amount of the funds in question. Despite this complete documentation, the payment platform suspended the account.
The suspension did not occur because a document was missing. It was not triggered by a failed bank verification or a flag from the IRS indicating a fake tax ID. Instead, the system applied a rule that was not even listed as a standard reason for suspension. The business had not broken this specific rule. In fact, the rule did not appear to exist in the standard guidelines. The automated system made its decision, and the mechanism offered no room for questions.
The business then filed an appeal. The platform promised a response within ten days. It took two weeks. When the response finally arrived, it was a denial. There was no detailed explanation. There was no reason provided. There was no human representative to call, no local office to visit, and no face to look at while the company explained why the business and its funds were no longer welcome.
It was simply a denial from an automated system.
The business had given the platform its identity, its tax records, its bank details, and the contract proving the money was real and the client was legitimate. In return, it received a suspension without a reason and an appeal without an explanation.
This situation is particularly frustrating because the terms are written in the platform's own contract, in its own words, on its own website. Section 12 of the General Terms of Service states that the company may terminate the terms or suspend the account at any time for any reason. The reason is optional. Section 13, which covers the effect of termination, says the company will not be liable to the user or any third party for compensation, reimbursement, or damages for any termination or suspension of the services.
The platform can take the account, hold the money, and disrupt the business, and it will not be liable.
The Payment Terms, Section 12, state that the company may defer payout or restrict access to proceeds, temporarily or indefinitely. This means the revenue from a client who has already paid can sit in the company's account while the system decides the fate of the business. Section 14, the Reserve for Holding Funds, says the company may require a reserve for any reason related to the use of the services. The amount of the reserve is reasonably determined by the company. It is not determined by a bank, a regulator, or a judge.
The most interesting part of the story is in Section 1 of the Payment Terms. It opens with a confession. The company states that it is not a bank. It describes itself as a payment facilitator, a processing company, and a software platform that takes payment and moves money. It is the pipe, not the reservoir. Yet this pipe has more power over the business than the bank that actually holds the money. The bank has to follow rules. The bank has to explain itself. The bank can be regulated. This software company has a suspension button, and the button has no off switch.
When a business tries to fight the decision, the contract is waiting. Section 22 of the General Terms prohibits class actions and juries. It requires individual arbitration in Oakland, California. Section 19 states that the total liability to the user is capped at the fees earned from the user in the three months before the problem, or $500, whichever is greater.
Five hundred dollars is the maximum value of the business according to the contract.
Section 7 says that if there is a dispute about who owns the account, the company will be the sole arbiter of such dispute in its sole discretion. Its decision will be final and binding on all parties. The company is the player, the referee, and the stadium.
This is the environment that has developed around digital commerce. A company that is not a bank acts like one. An automation system scrutinizes a business with zero reason and zero explanation. A merchant who did everything right, verified at every step, was suspended by a rule that was not even a reason for suspension. An appeal that took twice as long as promised died without a word.
The business cannot easily dispute it. To dispute it is to arbitrate, in the company's city, under the company's rules, for a prize capped at five hundred dollars.
The platform even has a list of unsupported industries in its Payment Terms. Item 6 on that list is direct marketing or subscription offers or services. A marketing and search engine optimization firm is one algorithmic mood away from that list. The machine does not need the rule to be true. It needs the rule to be convenient.
Where is the bank that has to explain itself? Where is the regulator that has to show its work? Where is the human being who has to look you in the eye and say the account was suspended and here is why?
There is no one. There is a dashboard. There is a denial. There is a machine that has never met the business, never read the contract, never spoken to the client, and has already decided.
This is not just a payment processor. It is a toll booth on the only road the business has. It is run by a company that is not a bank, governed by a contract that says it can do whatever it wants, whenever it wants, for any reason, and owe nothing for it.
The verified business did everything right. The platform did not need it to.
That is the whole story. That is the whole system. Until a company that is not a bank starts acting like one, every small business in the country is one algorithm away from losing its money, its account, and its voice, with no reason given and no explanation owed.
The verified business followed the rules. It provided the identity documents. It provided the tax documents. It provided the bank account. It provided the contract. The system said no. The system did not say why. The system did not say sorry. It just said no. And in the fine print, it said that was enough. The business had to accept that its money was now held by a software company that claimed no banking status but exercised banking power. The appeal process was a formality that took two weeks to produce a single word of denial. The contract said the company was not liable. The contract said the company was the final judge. The contract said the maximum compensation was five hundred dollars.
The business had a client. The client had paid. The money was real. The work was done. The documents were in order. The verification was complete. And still, the account was suspended. The reason was not listed. The explanation was not given. The human contact was not provided. The appeal was denied. The money was held. The business was stuck.
The platform's terms say it can suspend the account at any time for any reason. The terms say it is not liable for damages. The terms say it can hold funds indefinitely. The terms say it is not a bank. The terms say it is the sole arbiter. The terms say the liability is capped. The terms say the arbitration is in Oakland. The terms say the class action is prohibited. The terms say the decision is final.
The business had to read all of this after the fact. It had to find the sections. It had to understand the implications. It had to realize that the five hundred dollar cap was the limit of its recovery. It had to realize that the sole arbiter was the company itself. It had to realize that the suspension could be temporary or indefinite. It had to realize that the reason was optional.
The business did everything right. It submitted the ID. It submitted the EIN. It submitted the LLC documents. It submitted the bank link. It submitted the contract. It followed the instructions. It used the third party software. It verified the account. It waited for the approval. It received the suspension. It filed the appeal. It waited for the response. It received the denial. It read the terms. It understood the power imbalance. It accepted the outcome.
The system worked as designed. The machine made its decision. The contract enforced its rules. The company protected its interests. The business lost its funds. The client waited for payment. The business waited for an explanation. The explanation never came. The reason was never given. The mercy was never shown. The process was complete. The account was suspended. The money was held. The business was left alone.
More Business · Bad Service · Report a business · Got a Story?